A roof replacement insurance claim does one job well. It gets a new roof on your house after a storm has done real damage. What it doesn’t give you is much say in the details, like the product, the color, the timing, or how the project fits your life.
We work with insurance companies and we’re good at it, so this isn’t a warning against filing. It’s an honest look at the trade-off. In our experience, homeowners who plan their roof replacement and pay for it themselves, before something goes wrong, end up with more options and a result they’re happier with. Here’s how a roof replacement insurance claim compares with paying yourself.
Insurance work and retail work, in plain English
Insurance work starts with a covered event, usually hail or wind. You file a claim, an adjuster from your insurance company looks at the damage, and the claim sets the scope of the repair. On a roof, that’s a roof replacement insurance claim. You pay your deductible, and the insurance company pays the rest of an approved amount.
Retail work starts with you. You decide it’s time, or you decide you want a better roof, and you set the scope, the materials and the schedule. You agree on one price with your contractor and pay it directly. No adjuster, no claim.
Kinmount does both, and we do a lot more retail work than insurance work. We’re a preferred insurance contractor, so a roof replacement insurance claim is familiar territory for us. The difference isn’t the crew or the install. It’s how many choices you get to make along the way.
When a roof replacement insurance claim is the right call
We understand the emergency. A storm hits, there’s a tarp on the roof or water where it shouldn’t be, and you need it handled fast. That’s exactly what your policy is for. A roof replacement insurance claim usually makes sense when:
- A recent storm hit your area and you can point to damage that wasn’t there before
- The roof was otherwise in good shape, so the storm is the reason it needs work
- You’ve asked your agent or read your policy, and sudden storm damage is covered
- Your deductible is small compared with the cost of the repair
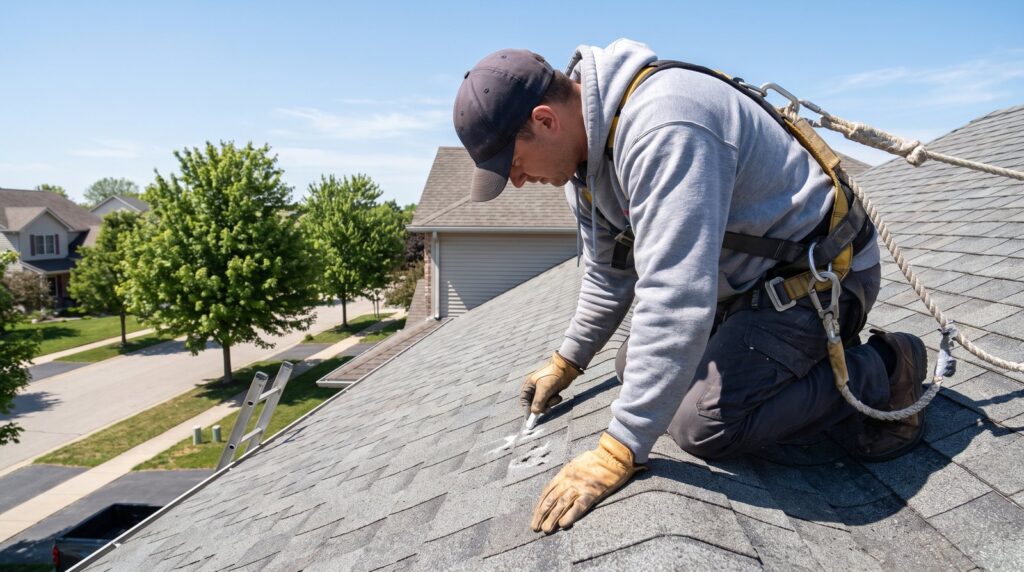
Damage isn’t always easy to see from the ground. Hail can bruise shingles and loosen their granules without leaving an obvious hole. A good roofer gets up there, looks closely, and photographs what’s really on the roof.
Our insurance company denied our shed but Craig came out and said there was hail damage. They worked with our insurance company and it ended up getting covered.
That’s from a review a Lakeville-area homeowner left for us. We share it because a second set of trained eyes is worth having before you file a roof replacement insurance claim, not to promise any outcome.
Where a roof replacement insurance claim limits your options
A claim is built for an emergency, so it works like one. It restores your home to the way it was, and the claim sets the boundaries. Your policy and your adjuster decide what’s covered, and that’s between you and your insurance company. Here’s where homeowners tell us they feel the limits:
- Scope – The repair follows the damage the adjuster approves, not the roof you would design if you could start fresh.
- Materials and color – Choices often follow what was on the house, so a step up to a premium shingle or a metal roof is usually something you’d cover yourself.
- Timing – The storm and the claim process set the schedule, and neither one checks your calendar.
- Time to decide – You’re picking a contractor, a product and a budget in the middle of a stressful week, with little room to compare.
None of that is a flaw in insurance. A claim exists to restore, not to upgrade.
What you control when you skip the roof replacement insurance claim and pay yourself
When you plan a replacement before a storm forces the issue, every decision is yours, and you get to make each one at your own pace:
- Timing – Pick the month that works with your family’s calendar, around the graduation party or the week at the lake.
- Product – Choose a better shingle, a metal roof, or whatever fits the house and the budget. See our residential roofing options.
- Color – Take samples home, look at them in daylight, and change your mind.
- Details – Add what you care about, like better ventilation, upgraded flashing, or new gutters while the crew is already there.
- Budget – See options at different price points and plan around what works. We offer financing as an option.
You also get time, which a roof replacement insurance claim rarely allows. You can visit our showroom, touch real samples, ask every question you have, and compare our itemized estimate with anyone else’s before you decide.
Roof replacement insurance claim or retail, side by side
| What to compare | Insurance claim | Paying yourself |
|---|---|---|
| It usually starts with | A storm and sudden damage | You deciding it’s time |
| Who sets the scope | The adjuster’s approved estimate | You, with our advice |
| Materials and color | Often follow what was on the house | Any option you like |
| Timing | Follows the claim and the weather | Whenever it suits your schedule |
| Time to plan | Short, because it’s an emergency | As long as you want |
| You pay | Your deductible, plus any upgrades you choose | One agreed, itemized price |
Why homeowners who plan ahead tend to be happier
We’re proud of the roofs we build either way, and homeowners are happy with both results. But in our experience, the people who choose retail, who plan ahead and pay for the work themselves, tend to be happier with the finished roof. The reason is simple. They had time. They saw samples, compared options, asked questions, and built a roof around how they live. They weren’t reacting to a storm or working inside a roof replacement insurance claim. They were deciding.
An insurance claim fixes what the storm broke. Planning ahead lets you build the roof you actually want.
That doesn’t mean waiting for a storm is a mistake. It just means the storm picks the day. If your roof is aging, you may be better off picking the day yourself. A few signs it’s time to start planning:
- The roof has needed more than one repair in the last few years
- Shingles are curling, cracking, or losing granules into your gutters
- You catch yourself watching the sky every time the weather turns
If you’re not sure, we’ll look at the roof and tell you honestly. If it has years left, we’ll say so. If it’s time to plan a replacement, we’ll walk you through your options with no pressure and no roof replacement insurance claim required.
The deductible promise you should never trust
After a big storm, a stranger may knock on your door and say they’ll cover your deductible, or that your roof will cost you nothing. That sounds like a gift, especially when a roof replacement insurance claim already feels like a lot. It’s a red flag.
Minnesota law doesn’t allow residential roofers to pay, waive, or promise to pay your insurance deductible as a way to win your business. You can read the rules in Minnesota Statute 325E.66. The same law says a roofer can’t interpret your policy or tell you what it covers. That’s between you and your insurance company, and we’d rather say so than pretend otherwise.
What we do when there’s a claim
If a storm did the damage and you decide to file a roof replacement insurance claim, we stay close without crowding you. We inspect the roof, document what we find, and write up the work in plain terms. Then we work with your adjuster so the repair reflects what’s actually on the roof.
Two things are worth asking your agent before you start: how long you have to report storm damage, and whether your policy pays a roof’s depreciated value first. Whatever the path, our ClearQuote™ Promise stays the same. Every line item is written out, so you can see what you’re paying for and compare it with any other estimate.
No pressure, whichever way you go
We show up in jeans and a t-shirt, and we don’t run a sales pitch at your kitchen table. If a storm did the damage, we’ll say so. If it’s just a tired roof, we’ll say that too. Our storm damage repair page shows how we handle storm work.
After a storm, start with our guide to the steps to take after a storm damages your roof. To see what homeowners say about working with us, visit our reviews page.
Common questions about a roof replacement insurance claim
Will my insurance cover my roof replacement?
It depends on your policy and on what caused the damage. Many policies cover sudden damage like hail or wind and don’t cover wear from age. Your insurance company decides coverage, so ask your agent or read your policy. We can inspect the roof and document what we find.
Does a roof replacement insurance claim raise my rates?
It can with some insurers, and some policies treat storm claims differently than others. Ask your agent how it works before you file. A call to understand your options is a good first step.
Can I upgrade my shingles with a roof replacement insurance claim?
Insurance generally pays to restore what was damaged, so a step up in product is usually something you’d pay for yourself. What your policy covers is between you and your insurance company, so ask your agent. If you want the most room to choose, a planned retail replacement gives you the most freedom.
Is it better to replace my roof before a storm?
If your roof is near the end of its life, planning ahead gives you control of the timing, product, color and budget, plus time to compare estimates. Waiting means the storm picks the day, and a roof replacement insurance claim sets the terms. We’ll give you an honest look at the roof, and if it has years left, we’ll tell you.
Can a roofer pay my deductible?
No. Minnesota law prohibits residential roofers from paying, waiving or promising to pay your deductible. A contractor who offers should make you cautious.
What if my claim is denied?
A denial doesn’t always mean there’s no damage. You can ask for a second look, and a documented inspection can help. If the roof is worn out regardless, a retail replacement is another option after a denied roof replacement insurance claim, and we’ll explain what that would look like.
Do I have to use the contractor my insurance company suggests?
No. You choose who works on your home. We’re a preferred insurance contractor, but the choice is yours. Read more about u003ca href=’/why-choosing-a-small-exterior-contractor-saves-you-thousands-over-big-name-companies/’u003ewhy a small contractor can save you thousandsu003c/au003e.